
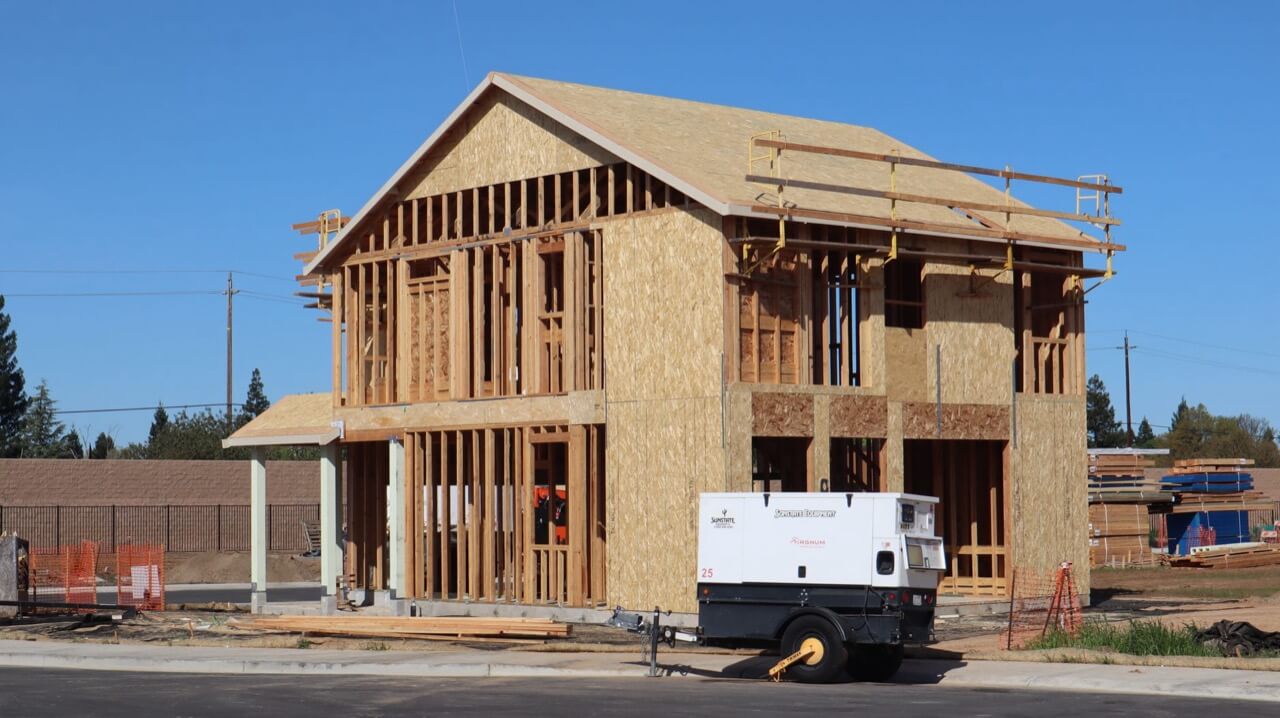
Three myths about building on land you own
You may think owning the land means you’ll qualify, the loan covers every cost, or construction financing automatically becomes a permanent mortgage. I’ll help you separate those assumptions from the questions your project needs answered.
What a construction loan on owned land does
A construction loan may fund eligible building costs, with the land and proposed project considered during the financing review. In Burlingame, California, the lender and program determine the loan structure and any conversion options.
Questions about your situation?
Talk it through with a loan officer who knows this market. No forms and no pressure.
Who this financing may fit in Burlingame
Planning a home that feels like yours can be exciting, but there’s a lot to coordinate. You may be weighing plans, builder contracts, project costs, and the timing of a current home or lease. I can help you think through how the land, project documents, and financing questions fit together. Getting clear on those questions early may make the next steps easier to manage.
Myth: Owning the land means you automatically qualify
You may feel that owning the site should settle the financing question. It matters, but it doesn’t decide qualification by itself. San Mateo County’s median household income was $156,000, according to the Census ACS 5-Year (2023); that community-wide figure doesn’t measure your ability to qualify. I’ll help you focus on the full review, including your finances, land, plans, and project feasibility.
Myth: The loan budget covers every building cost
You may be focused on the main construction estimate while smaller choices are still taking shape. San Mateo County’s median property tax was $9,167, according to the Census ACS 5-Year (2023); it’s local context, not a forecast of your tax bill. I’d review your estimates and ongoing costs with you, since upgrades and other expenses may affect how much financing you need.
Myth: Construction financing automatically becomes a permanent mortgage
You may hope to handle construction and long-term financing in one straightforward process. Burlingame’s home value was $2,845,047, according to Zillow Research (September 2026), but that doesn’t set your land’s value or determine your permanent loan terms. I’d clarify how completion, final documents, and permanent financing fit together before you rely on a particular structure.
The assumption I’d address first
It can feel natural to treat land ownership as the hardest part of financing. I’d first make sure we aren’t assuming the land alone settles the question. Your plans, full budget, property details, and construction schedule may all matter. I’ll help you flag open questions before the project moves forward.
What I see in this market
You may feel unsure about how owning the land affects your construction financing. I’ve worked in mortgages since 2002, and I help you sort through complex or tough files by looking at the financing questions your project raises. I work with borrowers exploring construction loans, along with other home and property financing options. As a native Californian who’s lived in Belmont for many years, I understand the value of local connections and bring that perspective to conversations about your financing. I help you work through the details of your file.
A local reference point for planning
You may be comparing building with nearby home values. Burlingame’s starter home value was $1,776,172, according to Zillow Research (September 2026). That’s a local reference, not a construction budget, land appraisal, or prediction of your finished home’s value. I’ll help you keep those distinctions clear.
Keep temporary housing in view
You may be coordinating construction with a lease, home sale, or move. Burlingame rent was $4,119, according to Zillow Research (September 2026). That can help you consider housing during the project, though your actual costs depend on your arrangements and schedule. I’d discuss timing alongside the financing milestones. I look at how your land, plans, budget, and construction milestones fit together, then flag questions we should resolve before the file moves forward. That’s especially useful when details are still changing or the project doesn’t fit a simple template.
Building versus buying can be a close decision
You may be weighing whether building is the right path. Burlingame’s price-to-rent ratio was 57.56, according to Derived (Zillow Research) (September 2026). It offers a local comparison of home values and rents, but it doesn’t tell you what your project will cost. I’d use it as context, then focus on your plans, budget, and financing review.
Can I get a construction loan if I already own the land?
Possibly, but owning the land doesn’t guarantee approval; approval is subject to credit approval and program guidelines, and the lender may also review your finances, plans, costs, and project feasibility. In Burlingame, the home value was $2,845,047, according to Zillow Research (September 2026), while San Mateo County’s median household income was $156,000, according to the Census ACS 5-Year (2023). Those local figures offer context, not a valuation of your land or a measure of your eligibility. I’ll help you understand what your specific review needs.
How does the lender pay the builder during construction?
The lender’s process depends on the loan terms; ask what milestones, documents, and approvals are required before funds are released. In Burlingame, rent was $4,119, according to Zillow Research (September 2026), which may help you think about housing costs while work is underway. It doesn’t predict your project schedule or explain your lender’s payment process. I’d encourage you to confirm both with the lender and builder early.
In this series
The numbers behind this page
Every figure comes from public data on Burlingame, CA and San Mateo County. Each one names its source and the month it describes, so you can check it yourself.
Last updated
